Quick Answer: Trade finance for importers in 2025 involves leveraging specialized financial instruments like Letters of Credit, Supply Chain Finance, and Purchase Order Financing to bridge working capital gaps, mitigate payment and performance risks, and optimize cash flow. This allows importers to secure goods, comply with international trade regulations, and expand operations without tying up precious cash reserves or incurring severe penalties from delays.
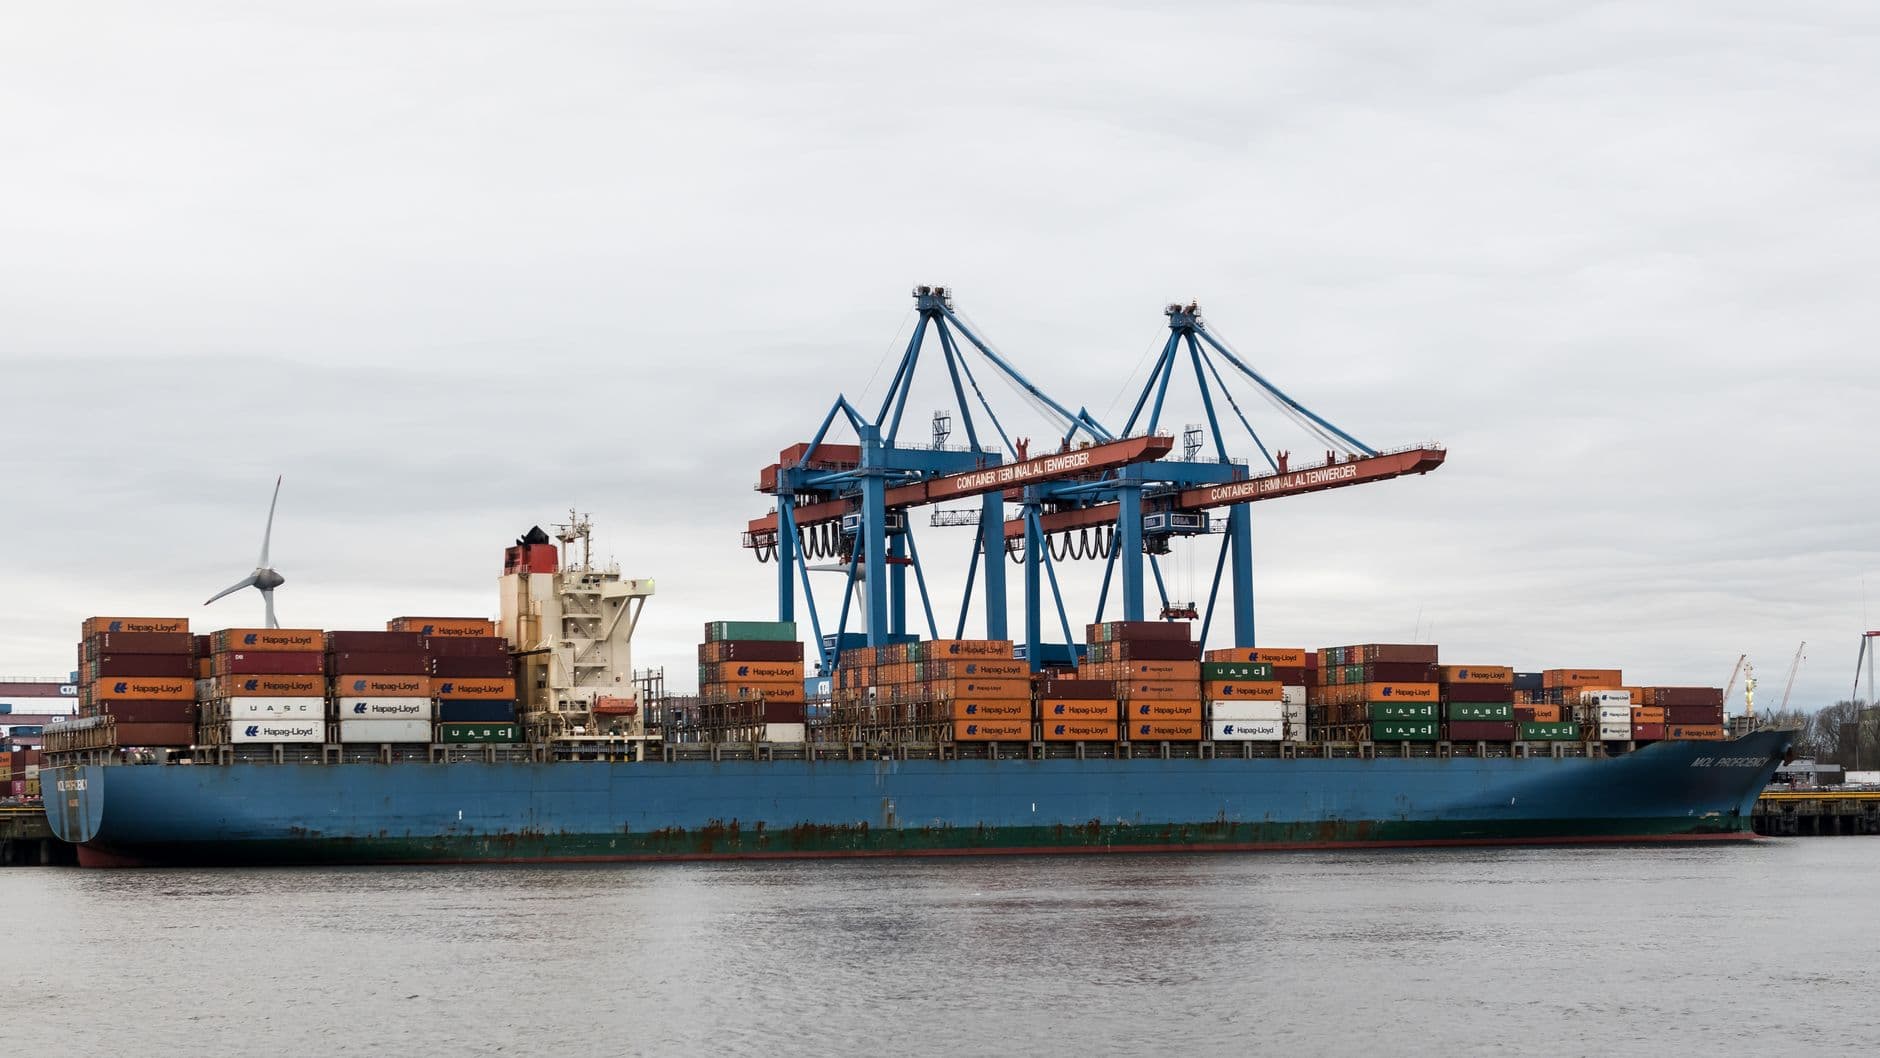
Your container sits at the port, accruing $350 per day in demurrage, not because of port congestion, but because your payment wasn't structured to clear customs efficiently. I've seen countless importers bleed thousands annually – up to $12,000 a year for smaller operators – due to financial bottlenecks and documentation errors that could have been avoided with strategic trade finance. It's not just about getting goods; it's about navigating the financial currents that can either sink your margins or propel your growth.
The Hidden Costs of Unoptimized Trade Finance for Importers
Many importers mistakenly view trade finance as a complex backend process rather than a strategic lever. This oversight is costing them dearly. Based on my 15 years moving freight, from dispatch to logistics management, I've seen firsthand how a lack of proper trade finance instruments exacerbates common supply chain pain points, turning minor hiccups into major financial hemorrhages. It’s not just about the cost of goods; it’s about the cost of capital, the cost of delays, and the cost of missed opportunities.
According to a 2023 survey by the International Chamber of Commerce (ICC), 65% of small and medium-sized enterprises (SMEs) in global trade struggle with access to finance, leading to an estimated $1.5 trillion trade finance gap annually. For importers, this often translates into lost inventory, missed seasonal peaks, and damaged supplier relationships.
Let's be blunt: that $12,000 annual hit I mentioned? It compounds. Imagine a single incorrect customs document or a delayed payment that holds up a 40-foot container. That's not just demurrage, which averages $100-$350 per day post-grace period at major US ports like LA/Long Beach. It's also warehousing fees, expedited shipping costs to recover the schedule, and potentially a lost customer if your product arrives too late. The root cause is frequently a mismatch between when you need to pay your supplier and when your buyers pay you. This working capital gap is where unoptimized trade finance creates its biggest headaches, forcing you into expensive short-term loans or, worse, halting growth.
Why Traditional Financing Fails Modern Importers
Conventional bank loans or lines of credit, while useful for general operations, often fall short for the unique cadence of international trade. They typically demand high collateral, lengthy approval processes, and lack the flexibility required for fluctuating shipment volumes or diverse supplier payment terms. For example, a supplier might demand 50% upfront payment, 30% upon shipment, and 20% on delivery – often before you've even received payment from your own customers. This upfront capital drain can paralyze an importer, especially in high-growth phases.
What many professionals miss is that this isn't just a cash flow problem; it's a risk management problem. When you're tied to traditional methods, you're exposing yourself to currency fluctuations, supplier default, and political instability without a safety net. The financial infrastructure of international trade has evolved precisely to address these specific risks, yet many importers cling to outdated practices, effectively leaving money on the table or taking unnecessary gambles.
Mastering Letters of Credit (LCs) for Importer Security
A Letter of Credit (LC) isn't just a fancy payment guarantee; it's your primary shield against supplier non-performance and a powerful tool to manage cash flow. In essence, your bank promises to pay the supplier once specific, agreed-upon documents proving shipment have been presented. This provides immense security for both parties. The common mistake I see? Importers accepting LCs drafted by suppliers, often containing vague terms that leave them vulnerable to disputes or payment for non-conforming goods.
Here's how to use LCs strategically:
- Specify Document Requirements to the Letter: Do not use generic terms like "shipping documents." Insist on specific documents: original Bill of Lading (BoL), commercial invoice, packing list, certificate of origin, inspection certificates (if applicable), and even specific phytosanitary certificates for agricultural goods. Make sure these document descriptions align perfectly with your customs clearance needs to avoid those $5,000+ fines for misdeclarations.
- Set Strict Presentation Deadlines: Negotiate for the latest possible document presentation date, allowing your goods time to arrive and for you to inspect documents thoroughly. A 21-day window post-shipment is a good target; anything less risks rushed, error-prone submissions.
- Insist on a Confirmed LC for High-Risk Suppliers/Regions: If you're dealing with a new supplier or importing from politically unstable regions, demand a 'confirmed' LC. This means a second, reputable bank (usually in your country) adds its guarantee, providing an additional layer of payment security should the issuing bank default. This isn't cheap, adding 0.5% to 2% to the LC fee, but it can save your entire shipment.
- Utilize Usance LCs for Cash Flow Management: Instead of immediate payment (sight LC), negotiate a 'usance' or time LC (e.g., "payable 90 days after sight"). This allows you to receive and even sell your goods before the payment to your supplier is due, drastically improving your working capital cycle. It's a game-changer for businesses with tight cash flow, often adding only 0.2% to 0.7% in additional bank charges compared to a sight LC.
The insider secret here? Many suppliers are willing to absorb a slight discount from a financing institution (factor) on a Usance LC if it guarantees payment from a reputable bank, allowing you to secure goods with terms that fit your cash flow.
Unlocking Working Capital with Supply Chain Finance & PO Financing
The biggest constraint for growth-oriented importers isn't demand; it's often the inability to fund larger orders or longer lead times. Supply Chain Finance (SCF) and Purchase Order (PO) Financing are two distinct but powerful tools to address this, transforming your working capital bottleneck into a strategic advantage. While both provide capital, their applications differ significantly, and knowing which to deploy is crucial.
Supply Chain Finance (Reverse Factoring)
SCF, often called reverse factoring, is initiated by the buyer (you, the importer). Instead of the supplier seeking financing, you approach a financial institution to finance your approved invoices with your suppliers.
- Your Role: Approve the invoice from your supplier.
- Financier's Role: Pays your supplier immediately (or within days) at a discount, offering your supplier favorable payment terms.
- Your Benefit: You still pay the financier on the original, extended payment terms (e.g., 60-90 days), effectively extending your payment window without harming your supplier's cash flow. This means your inventory arrives, gets processed, and possibly even sold before you need to make payment. Companies implementing SCF often see their days payable outstanding (DPO) increase by 30-40 days, freeing up millions in operating cash.
The often-missed advantage here is strengthening supplier relationships. By ensuring your suppliers get paid quickly, you become a preferred buyer, potentially securing better pricing or priority during supply chain crunch times. I've seen importers negotiate 2-5% price reductions from suppliers by offering SCF solutions.
Purchase Order (PO) Financing
PO financing, conversely, is for funding the purchase of goods *before* they are shipped. It’s ideal for importers who have secured a firm sales order from a creditworthy end-buyer but lack the upfront capital to pay their manufacturer.
- The Process: A PO finance company pays your supplier directly, up to a certain percentage (e.g., 80-90%) of the total PO value.
- Collateral: The financing is secured by the inventory being purchased and the ultimate sale to your customer, not your company's assets.
- Repayment: Once your end-buyer pays, the finance company takes its cut and remits the balance to you.
The crucial insight: PO financing isn't for every deal. It's best for transactions with clear, pre-sold orders and high-margin goods (typically 20-30% gross margin minimum to cover financing costs, which can range from 1.5% to 6% per 30 days). Don't use it for speculative inventory; that's a fast track to insolvency. This tool is purpose-built for fulfilling confirmed sales, preventing you from turning away lucrative deals due to capital constraints. For connecting with suppliers and ensuring smooth delivery of financed goods, a robust digital freight marketplace like Loadly can be invaluable, helping you secure competitive shipping rates after the PO financing closes.
Navigating FX Risk and Incoterms in 2025
Currency volatility can erode your profits faster than port congestion. A 2% swing in USD/EUR can wipe out your entire margin on a tight deal. Combine this with Incoterms confusion, and you're not just risking profits; you're inviting costly disputes and customs nightmares. Many importers rely on spot rates, which is akin to playing blackjack with your bottom line.
Proactive FX Risk Management
Forget praying the market moves your way. Implement these strategies:
- Forward Contracts: This is your simplest and most effective tool. Lock in an exchange rate for a future date (e.g., 30, 60, 90 days out) when you know you'll need to pay your supplier in their local currency. This eliminates uncertainty. Yes, you might miss a favorable market swing, but you also avoid devastating losses. The peace of mind alone is worth the typical 0.1-0.3% premium over the spot rate.
- Currency Options: For more sophisticated importers with higher volumes, options offer flexibility. You pay a premium for the right, but not the obligation, to exchange currency at a set rate. This allows you to benefit from favorable market moves while protecting against adverse ones. Consult with a specialized FX broker; this isn't a DIY solution.
- Netting: If you're both an importer and an exporter dealing in the same foreign currency, 'netting' your exposures can significantly reduce your overall FX risk and transaction costs. For example, if you receive EUR from exports and pay EUR for imports, you only convert the net difference.
The veteran move? Don't wait until payment is due. Hedge as soon as you confirm an order with a foreign supplier, or ideally, when you quote your customer in your local currency.
Incoterms 2025: Beyond Just Who Pays
Incoterms aren't just about freight costs; they dictate risk transfer, insurance responsibilities, and crucially, *when* you might need trade finance. Misunderstanding them is a top cause of customs delays and unexpected costs for importers.
- FOB (Free On Board): Most common for ocean freight. Seller delivers when goods are on board the vessel at the named port of shipment. Risk and cost transfer at this point. If you use FOB, ensure you have robust marine cargo insurance from the moment goods are on the ship.
- EXW (Ex Works): Seller makes goods available at their premises. Maximum responsibility for the importer. You're responsible for everything from pickup, export customs, and all transport. While it seems cheaper on paper, the complexity and potential for fines (e.g., for incorrect export documentation you're now responsible for) often outweigh the savings unless you have dedicated in-country logistics teams. I've seen EXW shipments incur 15-20% higher landed costs than initially planned due to unforeseen fees.
- DDP (Delivered Duty Paid): Seller is responsible for delivering goods to the named place in the buyer's country, ready for unloading, and pays all costs and risks, including duties and taxes. This is often preferred by new importers for simplicity, but you lose control and transparency over actual costs and delays. The "cost" is baked into the price, but you have no visibility into potential markups or inefficiencies.
My specific advice: For most importers, a balance like FCA (Free Carrier) at the supplier's factory or a nearby port is often ideal. It places less burden on you than EXW for export procedures but gives you control over main carriage and insurance, where you can often secure better rates than your supplier.
Trade Finance Instruments: A Quick Comparison for Importers
| Feature/Instrument | Letter of Credit (LC) | Supply Chain Finance (SCF) | Purchase Order (PO) Financing |
|---|---|---|---|
| Primary Goal | Mitigate payment/performance risk; payment guarantee | Extend buyer payment terms; optimize DPO | Fund pre-shipment goods; fulfill large orders |
| Who Initiates | Buyer (Importer) | Buyer (Importer) | Buyer (Importer) |
| Trigger Event | Contract/Order placed | Supplier invoice approved | Confirmed sales order from end-buyer |
| Key Benefit for Importer | Payment security, supplier trust, structured payment | Extended payment terms (e.g., 60-90 days), improved cash flow, stronger supplier ties | Capital for large orders without using existing credit, no asset collateral usually required |
| Key Risk Mitigation | Supplier non-performance, payment default | Supplier cash flow issues, payment delays | Inability to fulfill confirmed orders due to lack of capital |
| Typical Cost Range | 0.5% - 3.0% of shipment value (depending on type, bank) | 0.2% - 1.5% of invoice value (based on buyer's credit) | 1.5% - 6% per 30 days (higher risk, depends on margin) |
| Best Use Case | International transactions with new or high-risk suppliers, large orders requiring payment security | Optimizing working capital with stable, recurring suppliers; extending payment terms without impacting supplier | Funding specific, confirmed sales orders when you lack upfront cash for manufacturing/purchase |
Key Takeaways
- Unoptimized trade finance costs importers up to $12,000 annually in demurrage, fines, and lost sales from cash flow bottlenecks.
- Leverage Letters of Credit (LCs) with precise documentation and 'usance' terms to secure payments and extend your working capital cycle by 30-90 days.
- Deploy Supply Chain Finance (SCF) to extend your Days Payable Outstanding (DPO) by 30-40 days, freeing up capital and strengthening supplier relationships.
- Utilize Purchase Order (PO) Financing for pre-sold, high-margin orders to fund inventory acquisition without tying up your own capital.
- Hedge currency risk with forward contracts as soon as orders are confirmed to avoid losing 2-5% of your margin to FX volatility.
- Choose Incoterms strategically; FCA often offers a better balance of cost and control than EXW or DDP for experienced importers.
- Actively manage your working capital gap – the time between paying suppliers and receiving payment from customers – with tailored trade finance tools.
- Don't just track freight; integrate financial planning with your logistics to optimize total landed cost, not just shipping rates.
Frequently Asked Questions
What is trade finance for importers?
Trade finance for importers refers to the financial instruments and services designed to facilitate international trade by bridging capital gaps and mitigating risks between an importer and their supplier. These tools, such as Letters of Credit or Purchase Order financing, ensure timely payment to suppliers while allowing the importer to manage their cash flow efficiently and secure goods before full payment is due.
How can importers reduce customs delays and fines with trade finance?
Importers can reduce customs delays and fines by using trade finance instruments like Letters of Credit (LCs) to enforce strict, precise documentation requirements. By specifying exact document types and deadlines within the LC, you ensure suppliers provide customs-compliant paperwork, preventing issues like misdeclarations or missing certificates that commonly lead to $5,000+ fines and demurrage charges. Additionally, smooth financing prevents payment-related holds.
What is the difference between Supply Chain Finance and Purchase Order Financing?
Supply Chain Finance (SCF), or reverse factoring, is initiated by the buyer to help their suppliers get paid early on approved invoices, while the buyer maintains extended payment terms. Purchase Order (PO) Financing, however, funds the purchase of goods pre-shipment for an importer who has a confirmed sales order from an end-buyer. SCF focuses on optimizing payment terms for existing invoices, while PO financing focuses on funding the initial procurement of goods against a confirmed future sale.
When should an importer use a Letter of Credit versus an open account?
An importer should use a Letter of Credit (LC) when dealing with new suppliers, high-value shipments, or suppliers in politically unstable regions to mitigate payment and performance risk. LCs offer payment security and ensure goods meet specified quality and documentation standards. An open account, where payment is made after goods are received, is typically reserved for trusted, long-term supplier relationships where risk of non-payment or non-delivery is minimal, and established credit lines exist.
How do Incoterms affect trade finance for importers?
Incoterms define the responsibilities for cost, risk, and insurance during international shipping, directly impacting when an importer needs to deploy trade finance. For example, under EXW (Ex Works), the importer takes responsibility early, potentially needing pre-shipment financing. Under DDP (Delivered Duty Paid), the importer's financial obligation is delayed until goods arrive, but they lose control over costs and processes. Selecting the right Incoterm like FCA (Free Carrier) can align risk transfer with your financing strategy, optimizing cash flow and control.
Your 2025 Trade Finance for Importers Advantage
Navigating the complex waters of global trade requires more than just knowing freight rates; it demands a sophisticated understanding of financial instruments that can make or break your bottom line. We’ve peeled back the layers to show that problems like customs delays or unexpected capital drains aren't inevitable; they're often symptoms of unoptimized trade finance. By strategically deploying Letters of Credit, understanding the nuances of Supply Chain Finance versus PO Financing, and proactively managing FX risk, you can transform these challenges into opportunities for predictable, sustainable growth. It's about empowering your business to seize larger orders, expand into new markets, and achieve margins that truly reflect your efforts. If you're ready to move beyond traditional limitations and streamline your entire logistics and payment ecosystem, it's time to build your network and scale efficiently. Join Loadly and register for free today to connect with trusted partners and optimize your freight operations.